The coastline is only one part of the investment story
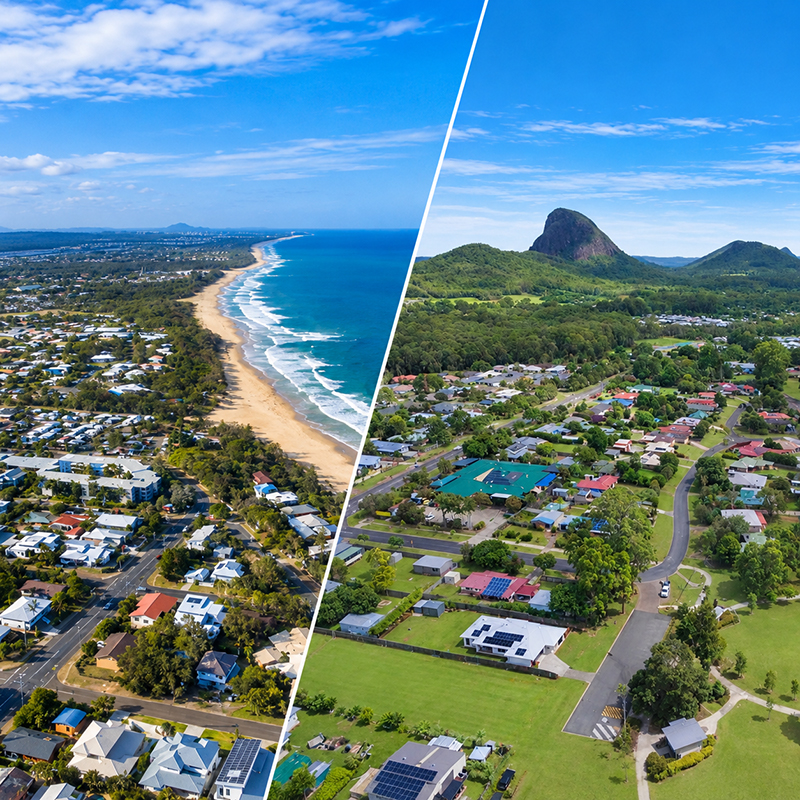
The Sunshine Coast is often discussed as a single lifestyle market, but the April 2026 report shows very different price and yield profiles across coastal, hinterland and growth corridor locations. Investors should start with the job the property needs to do rather than deciding that coastal or inland is automatically better.
A prestige coastal property may offer scarcity and strong owner occupier demand but a lower rental yield. An inland or growth area may offer a lower entry price and stronger yield but different supply and tenant dynamics. Both can work when the property matches the strategy.
Inland markets can offer a stronger entry price and yield equation
Nambour houses recorded a median of $868,600, 12 per cent one year growth and a 4.1 per cent median yield. Yandina was $1.06 million with a 4.3 per cent yield. Bells Creek was $945,000 with a 4.0 per cent yield. These figures can appeal to investors who want a lower capital outlay and more income support.
The trade off is that investors need to understand local supply, tenant profile and the quality of the exact pocket. Lower price should not be confused with low risk.
Coastal markets can carry a substantial premium
Noosa Heads houses recorded a $2.2425 million median with a 2.9 per cent yield. Mooloolaba was $1.7925 million with a 2.8 per cent yield, while Sunshine Beach reached $2.87 million with a 2.6 per cent yield.
Those lower yields reflect a much higher entry price. The attraction is often scarcity, lifestyle and deep owner occupier demand. For some investors, that is worth accepting. For others, the holding cost may not suit the strategy.
Growth is not confined to the beach
The report recorded 24 per cent one year house growth in Eumundi, 23 per cent in Birtinya, 19 per cent in Beerwah and 17 per cent in Pomona and Maroochydore. The pattern matters because it shows demand extending beyond traditional prestige coastal locations.
Again, these numbers describe the recent past. Investors should not chase them mechanically. The question is whether the drivers behind demand are durable and whether the property is still sensibly priced.
Infrastructure broadens the Coast’s employment base
The Sunshine Coast economy is increasingly supported by healthcare, education, technology, construction and professional services, in addition to tourism. The April 2026 report highlights the $5 billion health precinct, the Maroochydore city centre, airport expansion, transport investment and the international broadband network.
For property investors, this matters because a broader employment base can support more consistent housing demand. The best investments are still those that connect these regional drivers with a specific property that tenants and future buyers want.
Vacancy is tight in many locations
The report notes vacancy below 1 per cent in most sampled Sunshine Coast and Noosa markets. Caloundra units were 0.2 per cent, while Caloundra West, Coolum Beach and Maroochydore houses were 0.3 per cent. Noosa Heads units were higher at 2.0 per cent, which was still below the 3 per cent level often considered balanced.
Tight vacancy can support rents, but investors should avoid assuming the current level will last forever. Cash flow should remain sensible under more normal conditions.
Coastal versus inland is really a portfolio question
An investor seeking stronger cash flow may lean toward Nambour, Yandina, Bells Creek or other markets with higher reported yields. An investor with greater borrowing capacity and a preference for scarcity may consider coastal markets. Someone seeking a balance may look at established middle ring Sunshine Coast suburbs with both owner occupier and rental demand.
The decision is not ideological. It is about matching the asset to the investor’s finances, risk tolerance and holding period.
What I would check before buying either
For coastal property, check maintenance exposure, insurance, body corporate if applicable, parking, views, flood or coastal considerations and the depth of permanent resident demand. For inland property, check transport, employment access, competing new supply, tenant profile, land quality and local amenity.
In both cases, compare the property with relevant sales and understand the rental evidence before making an offer.
Do not overlook insurance and ownership costs
Coastal and newer growth area properties can have very different insurance, body corporate and maintenance profiles. Investors should obtain real quotes and review actual outgoings rather than relying on broad assumptions. The difference between gross and net return can be substantial.
This is particularly important when comparing a lower yielding prestige property with a higher yielding inland property. The headline yield is only the first line of the comparison.
A practical checklist before you commit
Before making an offer, return to the original brief and confirm that the property solves the problem you started with. Check the permanent features first, including location, street, land, access, orientation and surrounding uses. Then assess condition, improvements and the work you may need to complete after settlement.
Review the comparable sales, confirm your finance position, organise appropriate legal and technical advice and decide on your ceiling. A good property decision should still make sense when the pressure of the campaign is removed. That simple checklist is often more useful than trying to predict exactly what the market will do next.
FAQs
Can inland Sunshine Coast suburbs offer stronger yields? Yes. Several examples in the April 2026 report did.
Do coastal suburbs always grow faster? No. Recent growth was spread across coastal, inland and growth corridor markets.
What should investors compare? Entry price, yield, vacancy, tenant demand, supply, infrastructure and property quality.
Book a consultation with Murray McCarthy, for expert guidance on choosing between coastal and inland property for your Sunshine Coast investment.